Buffett’s Berkshire cuts BofA stake, adds to America's most-awarded airline
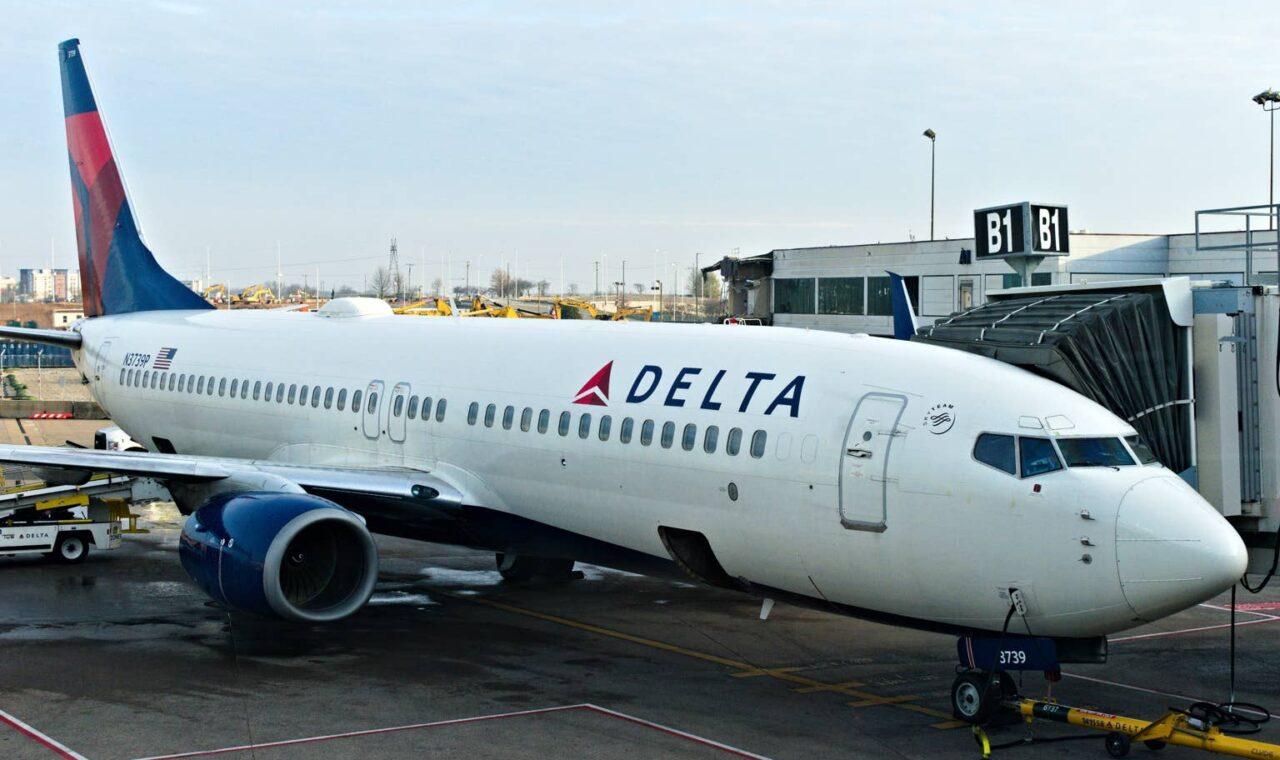
Delta is one of the airline industry’s most recognized brands and has earned praise for its passenger experience, customer service, operational performance, and workplace culture. In fact, it’s America’s most-awarded airline.
Berkshire Hathaway kept buying airline stock during a quarter when jet fuel was up 60%. Berkshire’s Q3 13F filing shows it raised its Delta Air Lines (DAL) position to 64.45 million shares from 57.32 million in Q2’s 13F.
It’s an addition of 7.13 million shares, or about 12%. In my last report, I covered the only new position in that filing, a $689 million stake in Bending Spoons. The Delta add is a quieter move, and arguably the more telling one.
Currently, DAL trades around $85, just below its all-time high of $95.68 from early July. It is up 22.90% year-to-date and 52.96% over the past 1 year, according to Yahoo Finance, against 7.04% and 9.82% for the S&P 500 over the same periods.
The filing shows Berkshire holding 64,450,000 Delta shares, up from 57,320,000 at the end of the prior quarter. That works out to 7,130,000 new shares.
Berkshire also trimmed its Bank of America stake in the same period, continuing the portfolio consolidation I covered in August under Greg Abel.
Selling a bank while adding an airline is a rotation, and 13F filings do not explain intent. Treat any “why” we give here as inference.
Also Read: United Airlines CEO warns of a growing problem for travelers
The Delta quarter Berkshire was buying into
The case for the stake is visible in Delta’s September quarter, reported Oct. 9. GAAP operating revenue was $20.2 billion, with operating income of $1.5 billion, a 7.2% margin, and pre-tax income of $1.1 billion. On an adjusted basis, revenue rose 16% to $17.6 billion, pre-tax profit was $1.5 billion, matching last year, and EPS was $1.72.
That profit held despite fuel. Adjusted fuel expense jumped 62%, or $1.6 billion, to $4.1 billion, with the average price up 60% to $3.61 a gallon. Non-fuel unit costs rose 7.3% on flat capacity.
More Airlines:
- Another airline in bankruptcy cancels all flights
- Irish airline shuts down and liquidates over jet fuel costs
- Another holiday airline in bankruptcy cancels all flights
I remember covering that fuel squeeze when Ed Bastian addressed Elon Musk‘s Starlink jab, and alongside United‘s $8 billion fuel increase.
“Demand remains strong, supported by consumers’ growing preference for experiences and travel,” Bastian said in the September quarter release. Delta also generated $1.9 billion of free cash flow year to date and plans to pay down more than $2 billion of debt in 2026.
We have a weaker side that needs to be addressed too. Delta lowered full-year adjusted EPS guidance to $5.10-$5.60 from $6.50-$7.50 and trimmed free cash flow guidance to about $2.5 billion from up to $4 billion.
It still expects roughly $4.5 billion in full-year pre-tax profit while absorbing a $6 billion fuel increase. December-quarter EPS is guided to $1.15-$1.65 on roughly 20% revenue growth, assuming jet fuel near $4.25.
Why an airline fits the Berkshire pattern, and where it doesn’t
Delta has been a long-time darling for Berkshire. Delta’s pitch is durability, according to its September quarter release. It led all carriers in on-time performance in North America in 2025, set a September-quarter record for domestic mishandled baggage, and won the Skytrax award for Best Airline Staff Service in North America for a fifth year.
Delta also earned a place on TIME’s America’s Best Companies list, making it the only airline among the top 100. It also ranked No. 1 on PEOPLE’s Companies That Care list, again standing as the only airline recognized.
Its loyalty ecosystem is growing, too, with SkyMiles membership led by Gen Z and millennials, and co-brand card satisfaction ranks at the top, according to J.D. Power. Management targets mid-teens margins and returns, durable free cash flow, and gross leverage of about one times.
United’s Scott Kirby said six to ten U.S. airlines would lose money this year. Delta is making a profit while some rivals are not, which is the kind of gap a patient investor looks for.
Still, airlines are cyclical, fuel-sensitive, and capital-intensive, which is not a classic Berkshire profile. A 12% increase on a multibillion-dollar position is also modest relative to Berkshire’s size, so I would not read it as a conviction signal on its own. Delta’s shares have also run to near-record highs, so the entry price is not low.
My takeaway on Delta is that a big investor added to the stock during a difficult fuel quarter, but I would want to see how the airline handles the next few months. The December-quarter results and whether fuel eases toward the $4.25 assumption will be important tests.